Dubai

We get startups ready for their venture round

We build the financial model, prepare investor materials and support pre‑seed, seed and Series A rounds for a fixed fee.

01Who we are

Two partners with 40+ years in deals, finance and venture

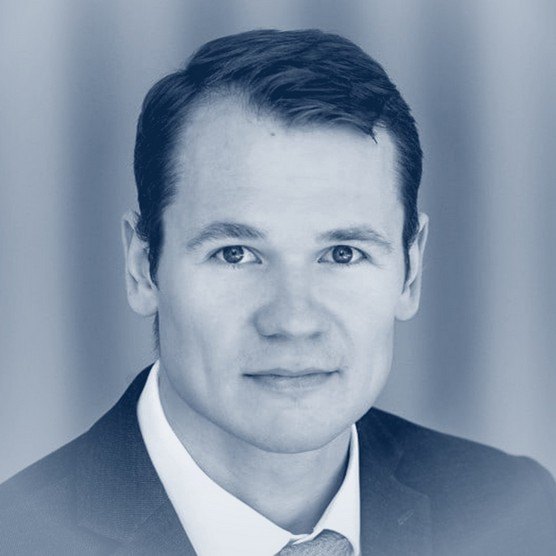
Portrait of Alexander Komov

Alexander Komov

Partner · Deals and round strategy

20 years in private equity, M&A and investment banking; CEO of a venture-backed digital health company.

20 yearsin PE, M&A and investment banking
$10B+in transactions
$10MSeries A for an AI telemedicine company
  • CEO and investment director, Doctor Ryadom (2020‑2024): $10M Series A, acquisition of Doc+ and two clinics
  • AFK Sistema (2012‑2018): acquisition of Segezha Group for $500M; 9.4x invested capital at the 2021 IPO
  • A1 (Alfa Group): acquisition of RusBioAlliance for $20M, $90M debt restructuring
  • Troika Dialog: Sberbank's $5.5B SPO, $4.6B MICEX‑RTS merger
  • Co-founder of Beauty‑Connect and DrillSense (Dubai); Moscow State University, London Business School
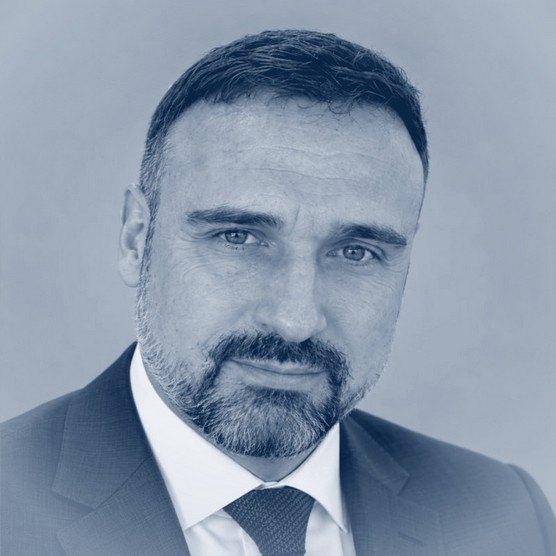
Portrait of Pavel Shcherbakov

Pavel Shcherbakov

Partner · Finance and round readiness

20+ years in corporate finance; as CFO of international companies, raised private financing for their growth.

20+ yearsin finance and management
$3.2B+of private non-bank financing
30+capital-raising deals
  • Group CFO of an electrical equipment group operating in 8 countries
  • CFO of a niche luxury carmaker: revenue +318%, month-end close cut from 12 to 5 days
  • CDO & CFO, FLEETCOR Russia: 3 acquisitions, EBITDA margin up from 73% to 78%
  • CFO, FIAT INDUSTRIAL CIS; Digital Finance Director, Groupe Renault; Michelin; PwC
  • INSEAD/CEDEP Executive MBA, ACCA DipIFR
02What we do

The full cycle: from financial model to signed term sheet

01

Round preparation

Financial model, unit economics, round size and valuation, use of funds.

02

Investor materials

Pitch deck, teaser, data room, answers to standard due diligence questions.

03

Investors

50‑100 funds, angels, family offices and corporate VCs that fit your round; introductions and preparation for every meeting.

04

Structure and negotiation

SAFE, convertible note or equity; term sheet, cap table, option pool.

05

Finance function

Part-time CFO: accounting, investor reporting, budgeting, cash flow.

06

Strategic deals

M&A, stake sales, partnerships and corporate investors at later stages.

Fixed fee for each stage. No percentage of the amount raised: we work for the founder.

03How we run a round

A pre‑seed or seed round: five stages, clear roles at each

Preparation · 4‑6 weeks
Support · 2‑4 months
DUCO's role
Founder's role
1 DiagnosticsWeek 1
DUCO's roleWe review accounting, banking, contracts, equity, SAFEs and loans, and list the gaps
Founder's roleGives access to accounts, contracts and the cap table
2 Model and valuationWeeks 2‑3
DUCO's roleWe build a three-scenario model and unit economics, and propose the round size, valuation and structure
Founder's roleApproves the plan, assumptions and round target
3 MaterialsWeeks 4‑6
DUCO's roleWe prepare the deck, the data room and answers to 30‑50 investor questions, and rehearse meetings
Founder's roleTells the company story and approves the materials
4 InvestorsMonths 1‑3
DUCO's roleWe draw up a list of 50‑100 investors, introduce you to those we know, prepare you for meetings and help answer their requests
Founder's roleHolds the meetings with investors
5 Term sheetClosing ~1 month
DUCO's roleWe compare term sheets, support the negotiation, review documents and update the cap table
Founder's roleChooses the terms and signs the documents

Pre‑seed and seed: what changes in preparation

Pre-seed
Seed
What investors assess
Pre-seedThe team, the problem and the prototype
SeedEarly proof of demand: customers, revenue, retention
Typical investors
Pre-seedBusiness angels, accelerators, pre‑seed funds
SeedSeed funds, angel syndicates, corporate VCs
Deal structure
Pre-seedUsually a SAFE or a convertible note
SeedA SAFE or a priced round
Key materials
Pre-seedDeck, 18‑24 month model, cap table
SeedPlus data room, cohort metrics, unit economics
DUCO focus
Pre-seedRound size and valuation, first deck, list of angels and funds
SeedModel and metrics, data room, list of 50‑100 investors, term sheet negotiation
Typical timeline
Pre-seed3‑4 months
Seed4‑6 months

From the start of preparation to closing.

04Deals

Selected deals of the partners

Venture financing: seven rounds, $73M

Predictive revenue intelligence and automated contract auditing for B2B enterprises

$15MSeries AInvestors: London-based enterprise VC funds, a US software executive2026

Fintech for cash-gap forecasting and liquidity

$11.5MSeries AInvestors: UAE fintech funds, US private investors2025

AI software for industrial design and physics simulation

$22MSeries AInvestors: industrial VC funds, family offices from Switzerland and Cyprus2024

Orchestration and security for corporate AI models

$4.5MSeedInvestors: early-stage tech funds, a US angel syndicate2024

AI platform for corporate knowledge bases

$7.2MSeedInvestors: pan-European VC funds, angels from the UAE and the UK2023

B2B procurement and supply-chain automation

$2.8MPre‑SeedInvestors: sector micro-funds, angels from Germany and the Netherlands2023

Doctor Ryadom

$10MSeries A2021

M&A, capital markets and corporate finance

Sberbank

$5.5BSPO2012

MICEX‑RTS

$4.6BExchange merger2011

Niche luxury carmaker

$600M+Sale to an investor and car plant acquisition

Segezha Group

$500MAcquisition from VTB2013

Electrical equipment group, 8 countries

$340MDebt and working-capital financing

A1 portfolio company

$90MDebt restructuring2019

RusBioAlliance

$20MAcquisition2019

UCL Chemicals

$15M+Minority stake sale

Benzuber

$5MAcquisition of a fuel payment app

FLEETCOR Russia (PPR)

100%Sale of the business2023

Nezavisimost

50%Sale of A1 and Goldman Sachs stakes

Legrand business in Ulyanovsk

M&AAcquisition and integration, plus companies in the CIS and Central Asia
05Founder mistakes

Six mistakes that cost founders the most

Each card says what to do instead. The full base has 18 mistakes, why each one costs money and where the figures come from.

01

Starting the raise when the money is about to run out

Start preparing while you still have more than a year of cash, and decide in advance the date by which you will cut costs if the round has not closed. The fund a16z calls raising with less than 12 months of runway a negative signal to the market.

04

A “hockey stick” model with nothing behind it

Build revenue from the bottom up: leads, conversion, customers, average check, churn. Use three scenarios, and give every assumption a source or your own data.

09

Several SAFEs and no idea how much of the company is left

Keep a cap table that shows ownership after all SAFEs and notes convert, and model the next round before signing a new SAFE.

12

Writing to investors who don't do your stage, check size or sector

Build a list of 50‑100 investors checked by stage, check size, sector, geography and deals in the last 12 months. Put funds that lead rounds first.

15

No data room when interest appears

Prepare the data room before the first meeting: corporate documents, cap table, financial statements, key contracts, IP, team agreements and answers to 30‑50 standard questions.

16

Looking only at the valuation in a term sheet

Compare term sheets by what each side receives if the company sells at 1x, 3x and 10x the round's valuation. Check the preference, anti-dilution, board seats and veto rights.

All 18 mistakes →
06Questions and answers

What founders ask us before we start

Why hire DUCO if we can raise the round ourselves?

Because investors rarely give a second chance. DocSend finds they spend less than three minutes on a deck, and a fund that has passed seldom comes back in the same round. We know what investors check because we have raised money ourselves. Alexander closed a $10M Series A as CEO of Doctor Ryadom and worked on more than $10B of deals. Pavel has raised over $3.2B of private financing, and in 2023‑2026 he found funding for more than 12 startups; funds have already sold a third of them at a profit.

What do we get in the first six weeks?

A financial model with three scenarios, a round size and valuation you can defend, a pitch deck, a data room and answers to the 30‑50 standard questions funds ask. In the very first week you get a list of gaps in your accounts, contracts and cap table that an investor would otherwise find in due diligence.

Will you introduce us to investors?

Yes. We draw up a list of 50‑100 funds, angels and family offices that invest at your stage and in your market, and introduce you to the ones we know personally. Before each meeting we tell you what that investor has already backed and what they will ask.

Can you help us get a higher valuation?

Yes, if the numbers back it. We build the case for your valuation: growth, unit economics and comparable deals in your market. Then we go through the term sheet line by line, especially the option pool and the liquidation preference: these lines often cost a founder more than a few points of valuation.

How fast can we raise?

Preparation takes 4‑6 weeks. A pre‑seed round usually closes 3‑4 months after we start, a seed round in 4‑6 months. A prepared company closes faster: it doesn't lose weeks fixing documents in the middle of due diligence.

When should we start?

A year before the money runs out. Rounds are now about two years apart: companies on Carta that raised a Series A in Q4 2024 had waited a median of 774 days since their previous round. With less than six months of cash, a founder negotiates under pressure and takes the first terms on the table.

How much does it cost?

A fixed fee for each stage, set by the size of the round. We take no percentage of the money raised, so all of it goes into growth. The first conversation is free: in an hour we look at your numbers, tell you what investors will ask about first and name the fee.

We already have a deck and a model. Why do we need you?

To make sure they survive the first meeting. We check the model against what investors expect at your stage, the deck against the standard questions funds ask, and the cap table, SAFEs and loans along the way. You can take only the stages you need, for example a model review or term sheet support.

Can we pay in equity instead of cash?

Yes, at an early stage. Instead of paying for preparation, the company gives us a small stake with vesting, and we stay on as its advisers until the next round. We agree the terms on the first call.

Will you stay with us after the round?

Yes. As your part-time CFO we run investor reporting, the budget and cash flow, and start preparing the next round from day one. Pavel runs finance for a group of companies in eight countries.

We work in your interest and bring all our experience, knowledge and energy to every round

The first conversation about your round is free. Write to either partner.

Alexander KomovPartner[email protected]+971 58 547 4400
Pavel ShcherbakovPartner[email protected]+90 537 268 6794Book appointment →
OfficeDUCOOpera Grand Tower, Floor 5, Office 513
11b, Sheikh Mohammed bin Rashid Boulevard
Downtown Dubai
Dubai, United Arab Emirates
duco.partners